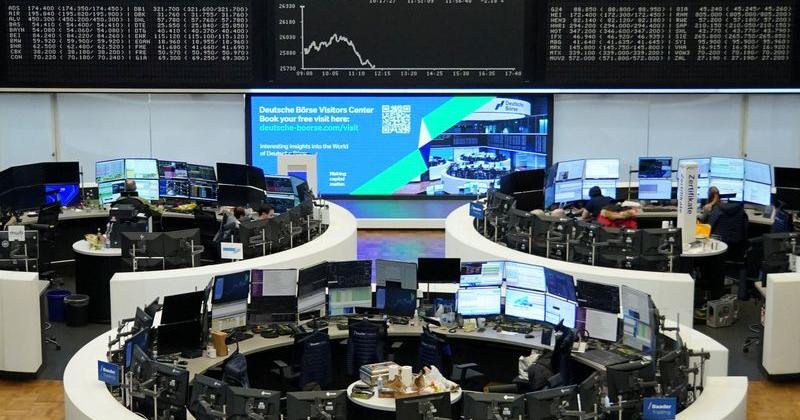
Europe’s benchmark STOXX 600 index slid from a record high on Thursday but posted a slight gain, buoyed by strong corporate earnings and a shift away from AI-related stocks in Asia and the United States. The pan-European index closed at 664.01 points, up 0.14%, after briefly reaching an all-time peak of 666.58 points earlier in the day. Meanwhile, oil prices rose, contributing to the positive sentiment.
The index’s performance has been underpinned by solid earnings this quarter, despite ongoing concerns over inflation and potential interest rate hikes. Oil, a significant import for Europe, rose on Thursday but remained below the $100 per barrel mark.
Aneeka Gupta, an equity strategist at WisdomTree, commented on market dynamics, stating, “If we are able to get a truce and an agreement between the US and Iran, that will help lower energy prices, which in turn should help allow for an improvement of sentiment among the European consumer.” She added that this could broaden the appeal of European equities.
Siemens experienced a gain of 1.7% after the company enhanced its mid-term growth forecasts. Adecco Group saw a significant rise of 14.7% following the announcement of stronger-than-expected third-quarter operating income, along with indications of improving conditions for permanent job placements.
Europe’s relatively lower exposure to AI stocks has contributed to its recent outperformance compared to peers in Asia and the US, as some investors are questioning the viability of the AI sector due to high valuations and potential regulatory changes after recent shifts in US politics.
Investors have shown a preference for defensive sectors, with the healthcare and consumer-focused industries—including food and beverage, travel and leisure, and retail—reporting double-digit gains this quarter.
In terms of annual performance, the energy and chemicals sectors have consistently outperformed, benefiting from higher commodity prices linked to ongoing geopolitical tensions, notably the conflict involving Iran.
Mark Preskett, senior portfolio manager at Morningstar Wealth Europe, noted, “The European market is home to a different set of companies, with greater exposure to consumer-facing businesses, industrials, and financials, driving outperformance during a period when technology stocks have struggled.”
Over the course of the quarter, the STOXX 600 has increased by nearly 5%, in contrast to the S&P 500, which has seen a decline of 0.2%. Analysts from Societe Generale reported that 13 of the benchmark’s 20 sectors have outperformed since the US midterm elections.
However, not all sectors have shared in the gains. Luxury goods and automotive sectors have lagged, each dropping more than 17% this year. The luxury market is facing weakened demand in China, while automakers such as Volkswagen and Volvo have reported significant drops in earnings due to increased competition from Chinese electric vehicle manufacturers.
Additionally, concerns linger regarding heightened government debt levels in France and Italy as crucial elections approach, which may test investor confidence. In the US, Nvidia’s resignation of CEO Jensen Huang has raised uncertainties about the future of the AI sector, contributing to a 0.5% decline in European tech shares.
