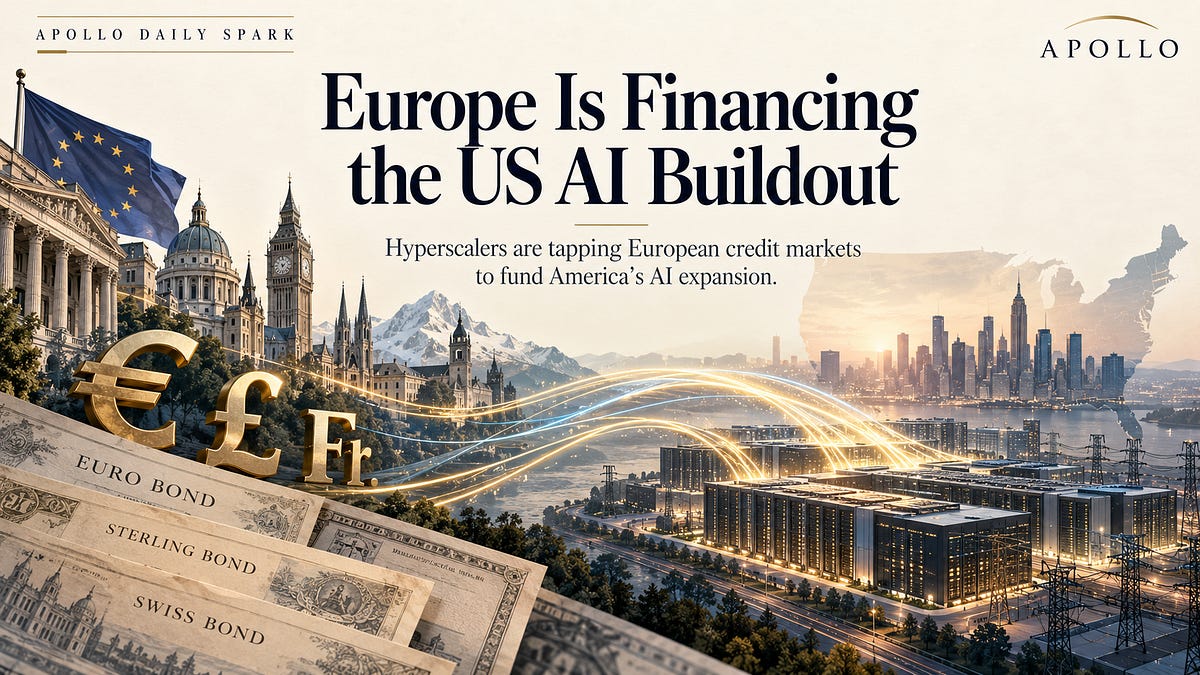
Hyperscaler companies are increasingly making their mark on European bond markets, raising $48 billion in bonds using various European currencies this year. This figure is more than triple the total raised in all of 2025 and breaks down into €27 billion, £13 billion, and CHF 7.5 billion.
Such issuance from hyperscalers, which include large tech and data center firms, now accounts for 3% of euro investment-grade (IG) bond issuance, 10% of sterling IG issuance, and 22% of Swiss franc IG issuance. In contrast, U.S. IG corporate issuance remains at 8% from hyperscalers.
Despite this significant influx of funds, there are currently no signs of crowding out in the bond market. Non-hyperscaler IG issuance has remained stable year-over-year, and corporate spreads have not widened. Instead, the participation of hyperscalers is enriching European credit indices by adding highly rated U.S. borrowers, typically rated AA- or higher, to segments of the market that have historically included more A to BBB-rated issuers.
Moreover, hyperscalers represent 7% of euro bonds with maturities exceeding ten years, a notable increase compared to the 3% average across all maturities. They also make up 3% of the 10-year-plus euro IG index, unlike a mere 1% of the overall index. This trend is beneficial as it provides more options for longer-dated maturities, which have been limited outside of sovereign issues. Interestingly, some governments, including the UK, have been shortening their bond issuance durations.
This trend shows no signs of slowing down. The scale of financing by hyperscalers is projected to rise another 25% by 2027, suggesting an even greater influence on European bond markets as these companies become a larger component of the credit indices.
The growing presence of hyperscalers in the bond market highlights the need to engage in diverse financing strategies, indicating a shift towards tapping both public and private financing sources.
