The European data centre landscape is evolving rapidly, driven by artificial intelligence (AI), digital sovereignty, and an increasing demand for local infrastructure. This shift is encouraging development beyond the established hubs of Frankfurt, London, Amsterdam, and Paris (collectively known as the FLAP markets).
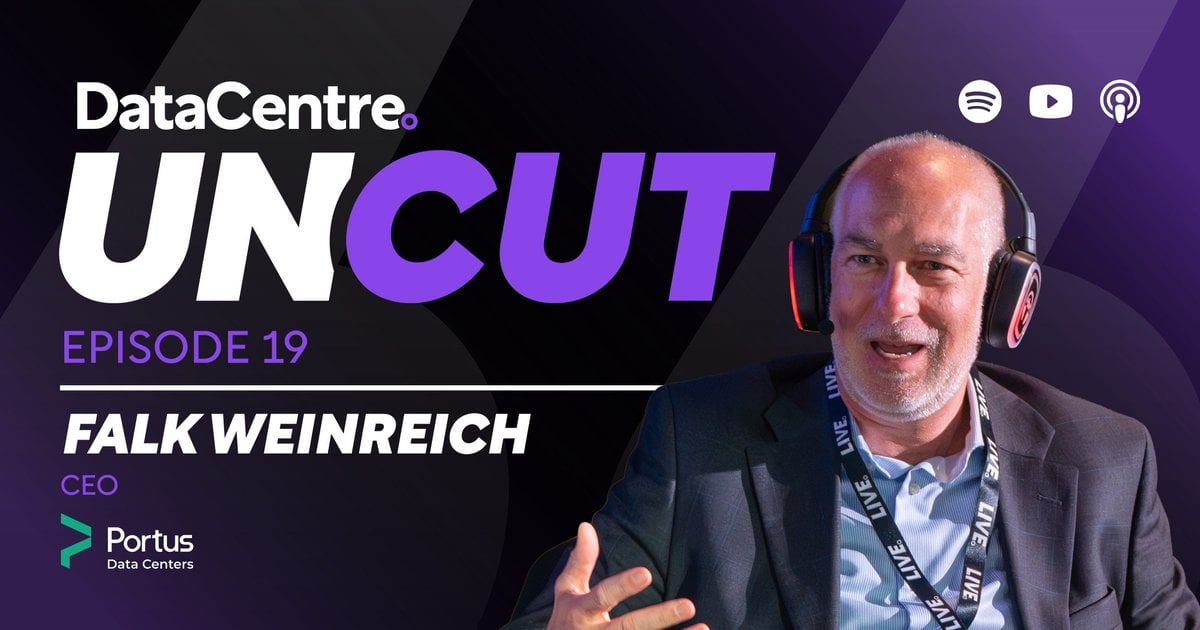
In the latest episode of Data Centre Uncut, guest host Tom Chapman interviews Falk Weinreich, Group CEO of Portus Data Centres, who shares insights on the expanding demand for data centres in regional markets and the implications for Europe’s digital infrastructure.
With nearly 30 years of experience in telecommunications, cloud computing, and data centres, Falk discusses how changing customer requirements, AI workloads, and energy limitations are creating new opportunities for regional operators. He emphasizes that flexibility, efficiency, and proximity to customers will be crucial as the industry grows.
Listeners can access the episode on various platforms, including Spotify, YouTube, and Apple Podcasts.
Key Developments in Europe’s Data Centre Market
- Expansion of data centre demand beyond the traditional FLAP markets.
- Impact of digital sovereignty on cloud and infrastructure decisions.
- Increased demand for regional and edge data centres driven by AI inference.
- Changes in facility design due to liquid cooling and higher-density workloads.
- Potential grid constraints that may limit infrastructure growth.
- Portus Data Centres’ expansion plans in Germany and Luxembourg.
- Future outlook for Europe’s data centre landscape by 2030.
Falk began his career during the deregulation of telecommunications in the 1990s and later moved into data centres and cloud infrastructure. After several years at OVHcloud, where he cultivated Central Europe’s enterprise business, he became the Group CEO of Portus Data Centres in September 2025, motivated by the potential in markets that have historically been under-invested.
Traditionally, data centre development has focused on the FLAP cities; however, Falk indicates a shift as businesses seek infrastructure closer to their operations. Germany, with its diverse industrial economy, presents a strong opportunity. Cities like Munich and Hamburg offer significant demand for digital services that have not been met compared to Frankfurt.
Digital sovereignty concerns, particularly regarding data ownership and control, are also reshaping infrastructure strategies. Organisations are increasingly looking into hybrid and private cloud environments to have more control over their sensitive data. This shift presents opportunities for colocation providers that can meet such demands efficiently.
Additionally, the rise of AI is pushing the need for regional data centres. Falk clarifies that AI training and inference require different focuses; while training demands high computing power and is best suited for places with favorable energy conditions, inference necessitates low latency and closer accessibility to end users.
Falk notes that the challenges associated with electricity availability could impact growth in the sector, as securing adequate power connections can take up to ten years. He urges that governments need to foster an environment supportive of infrastructure investment and enhance electricity networks to keep pace with the evolving digital demands.
Portus Data Centres is actively expanding its footprint, including plans for a new 12.8MW facility in Hamburg and an additional 5.5MW site in Munich. Falk also highlights potential expansions into cities such as Berlin, Düsseldorf, and Vienna. He predicts robust growth in regional markets driven by enterprise demand and AI needs by 2030.
Looking ahead, Falk aims to accelerate Portus’s expansion while enhancing operational efficiencies, emphasizing that the future of European data centres relies on balancing regional and centralized infrastructure to meet diverse customer requirements.
