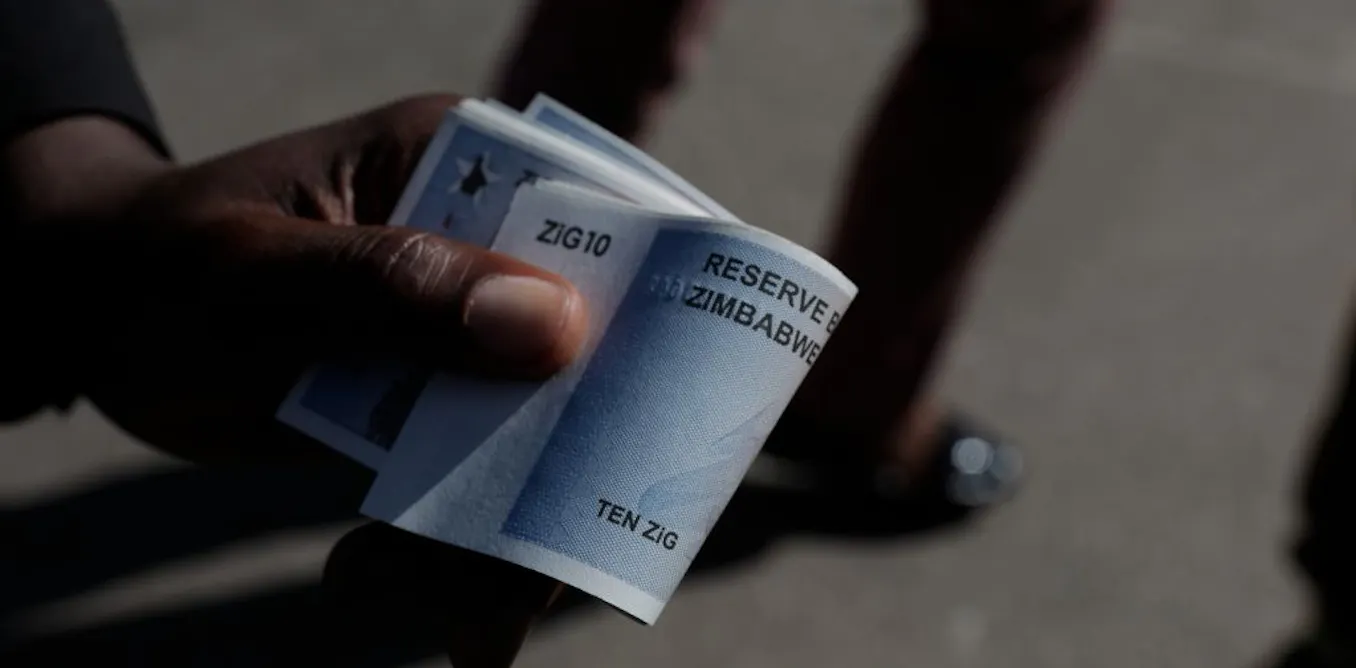
The Reserve Bank of Zimbabwe is pushing for greater adoption of the ZiG, a gold-backed currency launched in April 2024, through a new real-time payment system that draws on technology from India. This initiative aims to facilitate cheaper and faster transactions, enabling users to make purchases directly from their bank and mobile-money accounts.
Central to this effort is the Reserve Bank’s ongoing negotiations with NPCI International Payments, which operates India’s instant-payment system. The proposed payment platform intends to enhance payment efficiency and pave the way for potential cross-border transactions. However, experts emphasize that trust in the ZiG hinges on more than just technology; it requires a stable and attractive currency framework.
Three critical conditions are necessary for the ZiG’s success. First, Zimbabwean authorities must maintain control over the payment system to prevent external manipulation. The potential risks of foreign dependency on payment technology have been highlighted by numerous analysts, emphasizing the need for national sovereignty in financial systems.
Second, consumers should have the freedom to choose between the ZiG and the US dollar. Adoption should stem from convenience and stability rather than coercion. Lastly, the credibility of the Reserve Bank’s monetary policies is vital to building public trust. Zimbabwe’s historical context of currency instability, characterized by hyperinflation and volatile currency depreciation, has cultivated skepticism among its citizens.
Historically, Zimbabwe’s currency crisis has plagued the nation for over a decade, stemming from high levels of government spending and monetary mismanagement. The introduction of various local currencies, including bond notes and the recent ZiG, has not stabilized the economy, leading many to prefer holding US dollars for their perceived reliability.
As of September 2024, the Reserve Bank devalued the ZiG by 43% against the US dollar. Despite mandates requiring its use for certain taxes and government payments, widespread adoption remains elusive due to concerns over the government’s ability to excessively produce the currency.
While some recent indicators show signs of price stability, the ZiG’s overall inflation rate remains fragile. Current estimates indicate that price inflation was 3.7% in September, contrasting with slightly lower inflation across US dollar transactions. Additionally, as of the end of September, foreign reserves stood at approximately $2 billion, falling short of the Reserve Bank’s target for import cover.
In light of these challenges, the Reserve Bank has shifted its approach from aspirational timelines for currency transitions to a conditional framework, focusing on achieving stability before fully adopting the ZiG for domestic transactions.
Comparative observations from countries like Cambodia and Namibia show the potential benefits of creating effective and consumer-friendly payment systems. In Cambodia, the Bakong payment platform facilitates transactions in both local and foreign currencies without forcing a currency switch. Likewise, pilot testing of the Indian technology in Namibia suggests that well-designed payment systems can enhance local currency use while allowing currency choice.
Going forward, the success of the ZiG will depend on establishing an efficient payment infrastructure controlled by local entities, allowing for transparent operations that incentivize voluntary use of the ZiG, and maintaining sound monetary policies to foster public trust.
