The semiconductor sector has surpassed oil as the most significant dollar-related commodity flow in global trade, according to a research note from Deutsche Bank strategist Mallika Sachdeva. This shift indicates that the financial proceeds from semiconductor sales are being increasingly invested in U.S. stocks instead of government debt.
In a report dated November 16, Sachdeva emphasized that technological leadership is becoming a more crucial factor for the global standing of the dollar than geopolitical leverage. For the first time in modern history, the global trade in semiconductors is projected to exceed that of oil and gas during the four quarters ending in June 2026.
Asia’s surplus from semiconductor trade, particularly outside China, has reached levels similar to the surplus previously driven by oil from Gulf nations. However, the difference lies in the investment patterns of these earnings. Historically, through the petrodollar system established in 1974, oil-exporting nations reinvested their dollar earnings into U.S. Treasury bonds. In contrast, recent data shows that earnings from chip exports are being funneled primarily into U.S. equities.
Foreign investment in American stocks already surpassed $1 trillion over the past year, more than double the amount allocated to U.S. Treasuries, with Asia contributing the largest increase. South Korea exemplifies this trend, reporting a more than 200% increase in chip exports year over year, resulting in a trade surplus nearing $250 billion. Approximately 70% of South Korea’s overseas equity investments are now in U.S. stocks, with household investors allocating over 90% of their overseas equity holdings to American shares.
The influx of capital from semiconductor sales is facilitating the development of artificial intelligence infrastructure, which in turn generates more demand for components produced in Asia. According to the report, commitments for capital expenditure from hyperscalers are expected to reach nearly $8 trillion by 2031, potentially increasing semiconductor demand by an additional $4 trillion.
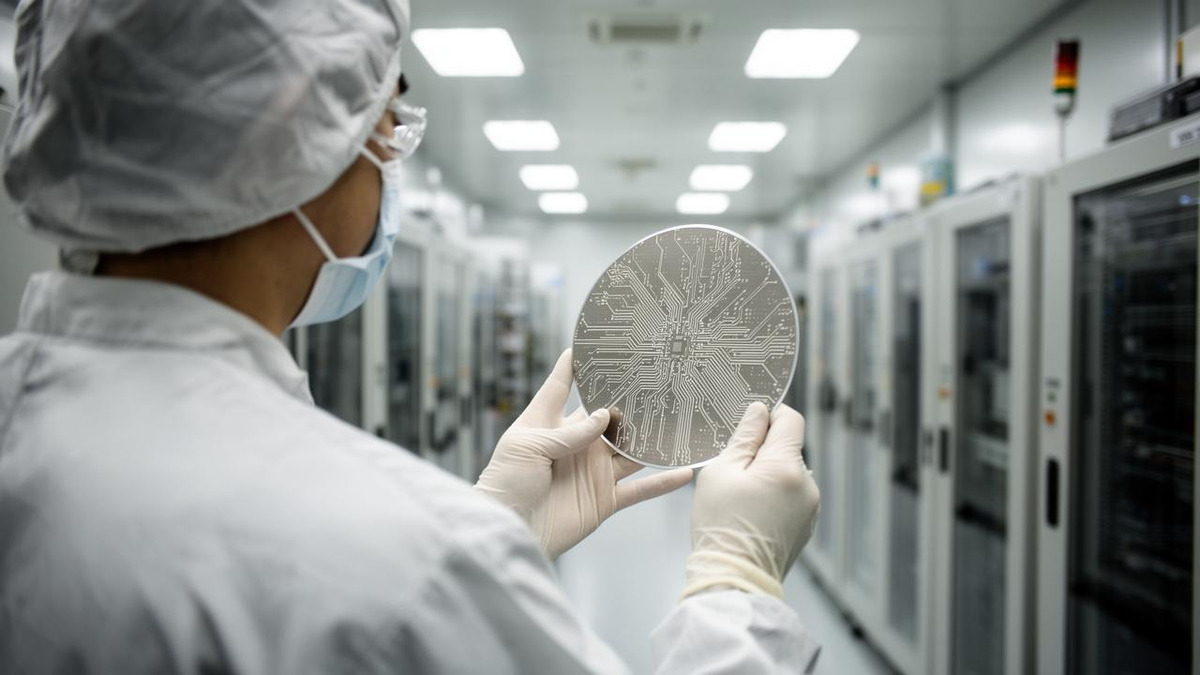
U.S. companies maintain significant control over the more lucrative segments of the semiconductor supply chain, capturing around 70% of industry profits. Research indicates that American firms are responsible for approximately 87% of chip-design revenue, underscoring their dominance in the sector.
The connection between dollar strength and the semiconductor industry is reminiscent of the role oil played in the past. Both are widely consumed and traded commodities. Chips, integral to modern devices and AI systems, constitute a substantial portion of expenses in data centers. According to the Semiconductor Industry Association, chips account for approximately 95% of costs tied to AI server architecture.
However, the dependence on chip demand raises questions about stability. Unlike oil, chips are replaced on cycles ranging from three to seven years, suggesting that demand could remain strong even after initial capital spending levels off. Despite this, the fluctuating nature of U.S. equities presents risks not associated with Treasuries, with tech stocks experiencing greater volatility. A downturn in AI infrastructure investment could simultaneously impact semiconductor demand, Asian export earnings, and foreign stock purchases.
This evolving relationship signifies that the dollar’s future may rely more on technology valuations and investor sentiment than on traditional reserve flow metrics. Additionally, structural changes within the U.S. financial system, such as potential asset tokenization and trading initiatives, could make it easier for foreign retail investors to access American stocks, further influencing these trends.
